
Conversational AI survey platforms are among the fastest-growing qualitative research methods available to buyers today, yet most organizations using them have not expanded beyond a small team. G2's analysis of 230+ verified Conversational AI Survey Platforms reviews shows the category averages 4.4 out of 5, 35% of buyers cite speed or time saved as their top benefit, and 83% go live in under a month.
Among buyers who reported deployment scale, however, 47% say fewer than a third of their users are on the platform. High satisfaction and limited scale are coexisting in the same category. The data reveals where these platforms are delivering, where buyers are pushing back, and what is keeping adoption narrow despite strong early results.
Yes. G2 Data shows that 35% of the 230+ verified reviews name speed or time saved as the best thing about the product. The time being saved is specific: verified buyers repeatedly report that manual transcription, tagging, and synthesis disappear, rather than survey creation getting faster. The implementation data confirms this. Of the verified reviewers who reported a go-live timeline, 83% were live in under a month and 29% in under a day. Among those who reported payback, 56% recovered their investment in less than six months. 73% of buyers who described their rollout did it with an in-house team rather than vendor or consultant services.
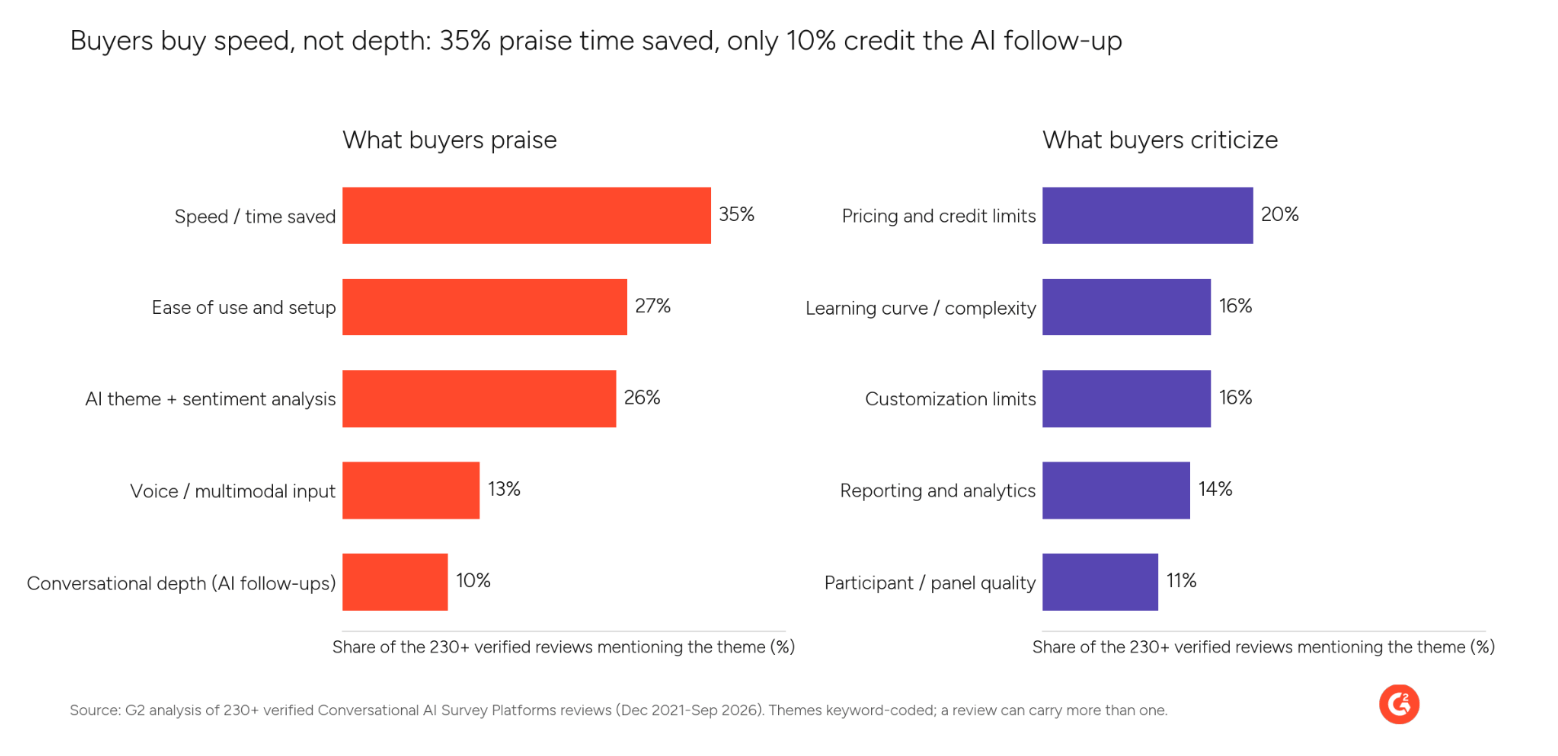
However, when the question comes to ‘are buyers actually valuing the conversational part of conversational AI’, it’s certainly not at the current stage. G2 Data shows only 10% of verified reviews mention the AI's follow-up questioning, probing, or conversational feel as what they like best, the capability that separates these platforms from traditional survey tools. Speed, ease of use, setup, and ability to run automated sentiment analysis dominate instead. This tells vendors where buyers are finding value today and where the category still has room to differentiate.
For vendors, this is an important product signal: the data suggest that buyers currently place more value on the efficiency and automation these platforms deliver than on the conversational AI itself. That does not necessarily mean buyers do not value the conversational capability; it may simply be too early to draw that conclusion.
According to G2's analysis, 65% of buyers award 4.5 or 5 stars, yet 47% report that fewer than a third of their users are on the platform. There is also a fundamental difference between completing a traditional survey and interacting with an AI chatbot. Conversational surveys need real-time contextual responses, which introduces friction and can reduce the quality of structured feedback.
Across all six satisfaction sub-scores, every metric scored above 6 out of 7. Hence, satisfaction is not the constraint. The real constraint is adoption.
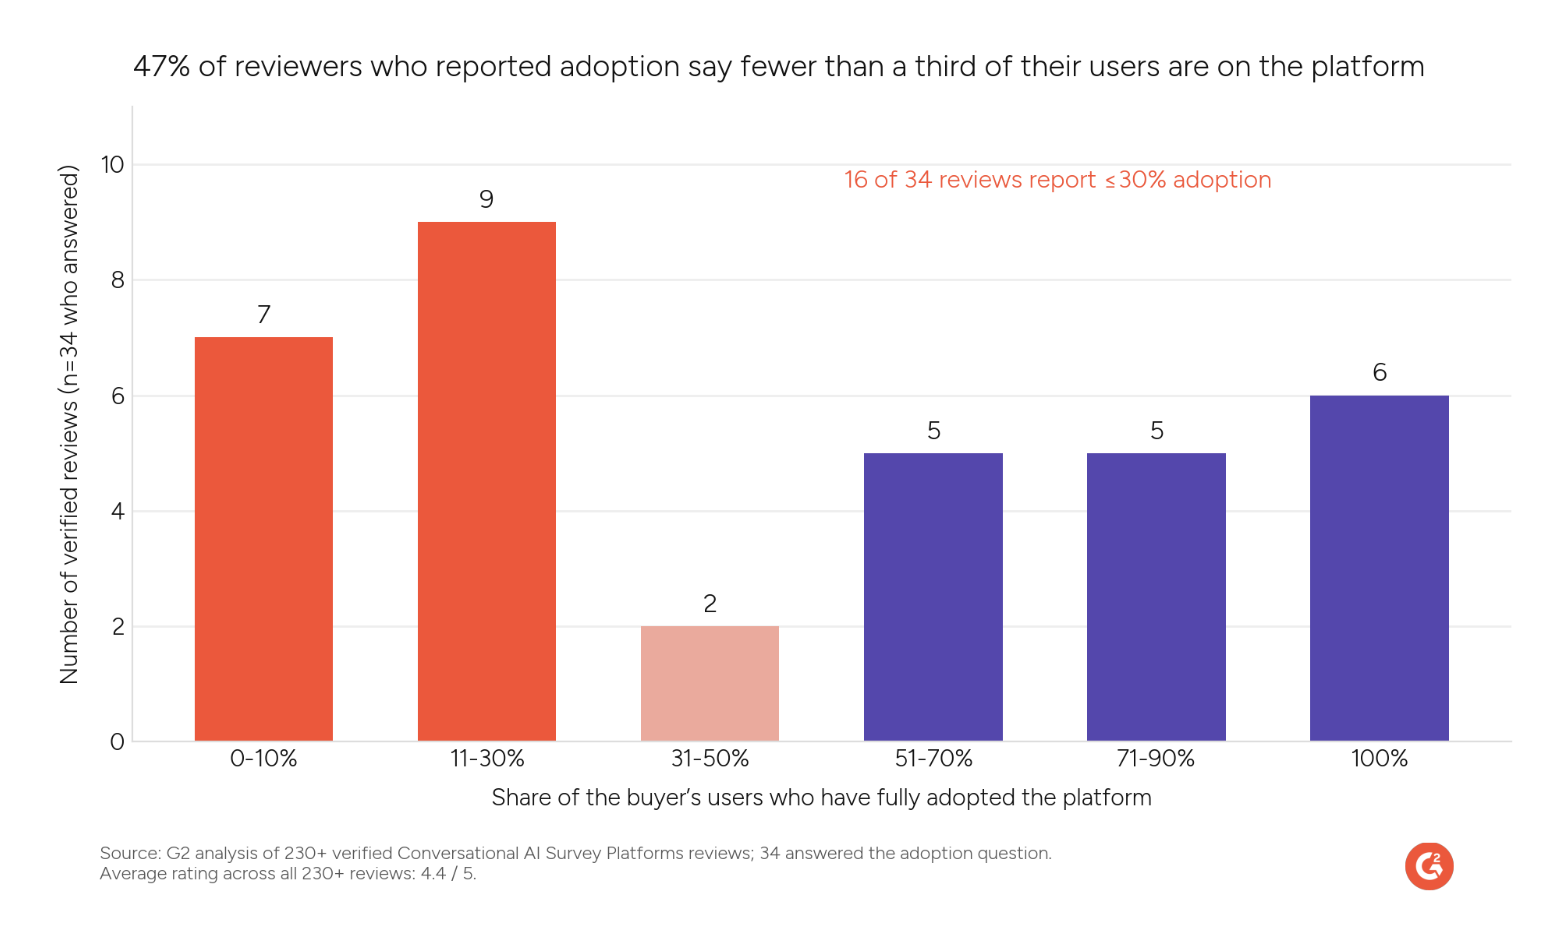
Among verified reviewers who reported what share of their users had fully adopted the platform, 47% said 30% or less, and 21% said 10% or less; only a third reported adoption above 70%. G2 Data suggests these platforms are being adopted as specialized tools for an insights or product team rather than as a company-wide infrastructure.
The most disliked themes in user reviews of Conversational AI survey platforms are pricing, reporting & analytics, customization limits, and learning curve. Among all, pricing leads overall.
G2 Data show that, across small, mid-market, and enterprise businesses, an average of 20% of verified reviews cite price, credit limits, or plan tiers as their main dislike, and this does not fade with satisfaction: 16% of reviewers who gave 4.5 or 5 stars still flagged cost. Usage-based credit models draw the sharpest language, with verified buyers describing tiers that "scale up aggressively" with volume and advanced features such as conditional logic, multi-variant testing, role-based access, and other features "locked behind higher-tier plans."
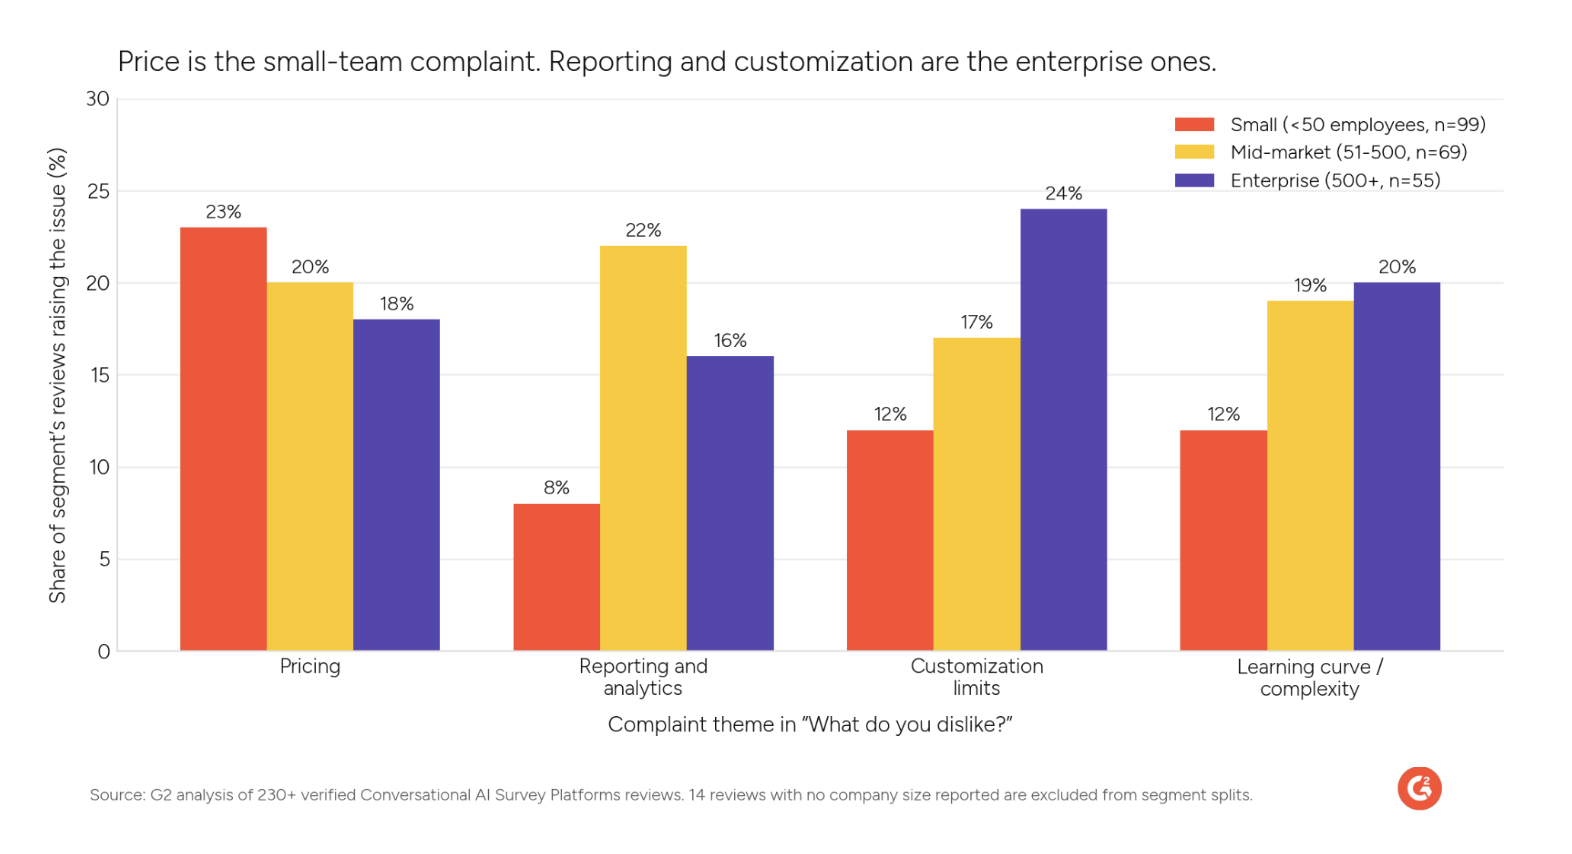
Among all 230+ verified reviewers, 47% of the total reviewers are from small businesses, and among small businesses, 23% raise pricing and only 8% raise reporting. Among mid-market buyers, reporting and analytics jump to 22%. Among enterprise buyers, customization limits lead at 24%.
No, not yet. G2Data shows that only 6% of verified reviewers switched to a conversational AI survey platform from another software product, while 59% explicitly said they did not switch. This reframes the 2026 competitive picture: these platforms are not yet primarily winning displacement deals against traditional survey software. Instead, they are entering organizations as a new line item, enabling work that previously was not being done at all.
Two factors may help explain this dynamic.
First, users may still be building confidence in these relatively new tools and their ability to deliver reliable outcomes.
Second, pricing remains a significant constraint in the buying journey, which can further limit adoption and make it harder for conversational AI survey platforms to replace established software.
Conversational AI survey platforms are software that uses AI, NLP, and machine learning to run dynamic, context-aware surveys and interviews. Based on the G2 Grid® for Conversational AI Survey Platforms, Prolific, ElevenLabs, G2 Marketing Solutions, and Maze are among the best platforms for users' survey needs.
Traditional survey tools and basic chatbots rely on fixed question sequences and simple question-and-answer logic. Conversational AI survey platforms use NLP and agentic AI to hold natural, dialogue-driven conversations that adapt in real time, closer to a human-led interview than a static form.
Not entirely. These platforms can moderate large numbers of interviews simultaneously, generate adaptive follow-up questions, and automatically synthesize themes from open-ended responses. Human researchers are still needed to design the research strategy, interpret ambiguous or sensitive findings, and make final decisions based on the results.
They let teams run qualitative research at a scale that would be impractical with human moderators, since interviews can happen simultaneously across large respondent pools. They also cut research turnaround time by automating transcription, thematic coding, and insight synthesis, and they support richer data collection through voice, video, and interactive stimuli rather than text-only forms.
Research, CX, and marketing teams use these platforms to gather deeper qualitative insights than traditional methods allow. Common use cases include running AI-moderated in-depth interviews that adapt to participants in real time, conducting large-scale qualitative studies with automated thematic coding, and collecting multi-modal feedback through voice, video, and interactive stimuli across distributed audiences.
These platforms commonly connect to CRM software, help desk platforms, and conversational intelligence tools, pulling in participant or customer context to make interviews more relevant. That integration lets the platform tailor questions to a respondent's history, and route synthesized insights back into the systems teams already use for analysis or follow-up.
Buyers are rewarding these platforms for speed and time-to-value, but the conversational interviewing capability that defines the category remains underutilized. Buyers evaluating this category in 2026 should ask vendors to show not just the speed of setup but also evidence of sustained team-wide adoption.
To drive sustained usage, vendors will need to address practical barriers such as pricing models, reporting capabilities, and support quality.
Explore the G2 Grid for the top-rated Conversation Intelligence Software.